Knowing how much cash your business has today is important. Knowing how much cash you are likely to have next month, next quarter, or later in the year can be even more valuable.
That is the purpose of cash flow forecasting.
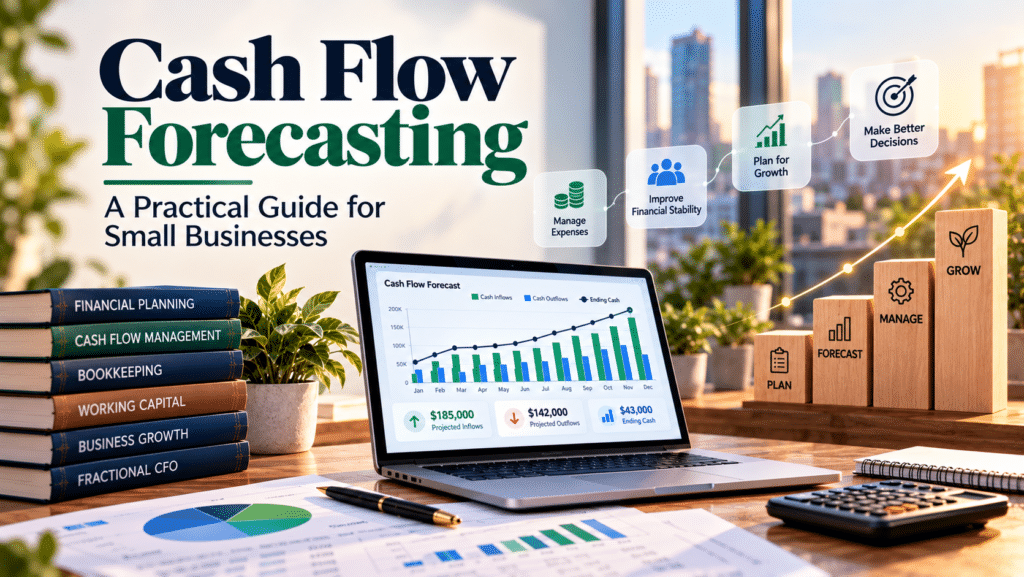
A cash flow forecast estimates future cash coming into and going out of a business. It helps owners identify potential cash shortages, plan upcoming expenses, manage working capital, evaluate growth opportunities, and make financial decisions before problems become urgent.
A business can have strong sales and still experience a cash shortage if customers pay slowly, inventory absorbs cash, or several large expenses become due at the same time.
This guide explains what cash flow forecasting is, how to create a forecast, what to include, how to improve its accuracy, and how to use it for better business decisions.
What Is Cash Flow Forecasting?
Cash flow forecasting is the process of estimating a business’s future cash inflows and cash outflows over a specific period.
A basic cash flow forecast follows this structure:
Opening Cash + Expected Cash Inflows − Expected Cash Outflows = Projected Closing Cash
Cash inflows may include:
Customer payments
Cash sales
Accounts receivable collections
Loans
Investment proceeds
Grants
Asset sales
Other expected receipts
Cash outflows may include:
Payroll
Rent
Supplier payments
Taxes
Insurance
Loan payments
Software subscriptions
Inventory purchases
Marketing expenses
Equipment purchases
Other operating costs
The result gives business owners a forward-looking view of liquidity rather than simply showing what happened in the past.
Timber Wolf’s existing small-business forecasting guidance similarly emphasizes opening cash, expected collections, operating expenses, taxes, debt, capital purchases, and projected closing cash as core components of a useful forecast.
Why Is Cash Flow Forecasting Important?
Cash flow forecasting helps answer questions that a traditional profit-and-loss statement cannot answer on its own.
For example:
Will we have enough cash to cover payroll next month?
Can we afford to hire another employee?
When will a large customer payment arrive?
Can we purchase new equipment without creating a cash shortage?
How much working capital will we need during a slow period?
What happens if revenue falls below expectations?
These questions are about future liquidity.
The U.S.A Small Business Administration recommends using financial projections to understand future business performance and specifically highlights projected cash flow as part of financial planning.
Cash Flow Forecast vs. Cash Flow Statement
These two reports are related, but they serve different purposes.
Cash Flow Statement
A cash flow statement explains what happened to cash during a past period.
Cash Flow Forecast
A cash flow forecast estimates what may happen to cash in a future period.
In simple terms:
Cash flow statement = looking backward
Cash flow forecast = looking forward
A business needs both.
Historical financial statements provide the information used to build realistic assumptions, while the forecast helps management plan what comes next.
What Should a Cash Flow Forecast Include?
A useful forecast should include more than expected sales.
1. Opening Cash Balance
Start with the cash actually available at the beginning of the forecast period.
Use reliable bank and financial records rather than an estimated number.
2. Customer Collections
Estimate when customers are actually expected to pay.
This is important because an invoice does not automatically mean cash is available.
For example, if you invoice a customer $30,000 in January but the customer pays in March, the revenue and cash timing are different.
3. Operating Expenses
Include recurring expenses such as:
Payroll
Rent
Utilities
Insurance
Software
Marketing
Professional services
4. Accounts Payable
Consider when supplier invoices and other bills will actually be paid.
Payment timing can significantly affect short-term liquidity.
5. Taxes and Debt Payments
Do not overlook irregular or periodic obligations.
Include expected:
Tax payments
Loan repayments
Interest
Insurance premiums
Annual subscriptions
6. Capital Expenditures
Large purchases such as equipment, vehicles, technology, or property can create substantial cash outflows.
These should be included in the period when the cash is expected to leave the business.
How to Create a Cash Flow Forecast Step by Step
Step 1: Start With Accurate Financial Records
Your forecast is only as reliable as the information behind it.
Begin with current:
Bank balances
Accounts receivable
Accounts payable
Sales data
Payroll information
Recurring expenses
Debt obligations
Tax obligations
This is where accurate bookkeeping becomes essential.
If the books are incomplete or outdated, future projections can be based on incorrect assumptions.
Step 2: Estimate Future Cash Inflows
Do not simply copy your revenue forecast.
Estimate when money will actually be collected.
Review:
Existing invoices
Customer payment terms
Historical collection patterns
Recurring customers
Expected new sales
Seasonal demand
For businesses with significant receivables, accounts receivable management can have a major effect on cash availability.
Step 3: List Future Cash Outflows
Create a complete schedule of expected expenses.
Separate them into:
Recurring expenses
Payroll, rent, subscriptions, insurance, etc.
Variable expenses
Materials, commissions, shipping, transaction fees, etc.
One-time expenses
Equipment, legal fees, renovations, major technology purchases, etc.
Step 4: Add Timing
Timing is one of the most important parts of cash flow forecasting.
Two businesses can generate identical annual revenue but have completely different cash positions if their customers pay at different speeds.
This is why cash flow forecasting should focus on when cash moves, not just how much revenue the business generates.
Step 5: Calculate Projected Closing Cash
Use:
Opening Cash + Inflows − Outflows = Closing Cash
Repeat this calculation for each week or month in your forecast.
This makes potential cash gaps easier to identify.
Step 6: Compare Forecast With Actual Results
At the end of each period, compare what you predicted with what actually happened.
Look for differences in:
Sales
Collections
Payroll
Operating expenses
Supplier payments
Taxes
Capital expenditures
This process is called variance analysis.
The goal is not to produce a perfect forecast.
The goal is to understand why your assumptions were different from reality and improve the next forecast.
How Often Should You Update a Cash Flow Forecast?
The right frequency depends on the business.
Weekly Forecasting
Useful when:
Cash is tight
Revenue is volatile
Customer payments are unpredictable
The company is experiencing rapid growth
Large payments are approaching
Monthly Forecasting
Works well for many established small businesses.
A monthly forecast provides enough detail for most budgeting and planning decisions without creating excessive administrative work.
Quarterly Forecasting
Can be useful for longer-term strategic planning, although businesses should generally maintain a more detailed short-term view when cash is sensitive.
A good rule is:
The greater the uncertainty, the more frequently you should review cash.
Timber Wolf’s existing guidance similarly recommends weekly forecasting for tighter or more volatile cash positions and monthly forecasting for many established businesses.
Use Three Cash Flow Scenarios
One of the strongest ways to improve cash flow planning is to stop relying on a single forecast.
Create three scenarios.
Base Case
Your most realistic expectation based on current information.
Best Case
Assumes stronger sales, faster collections, or lower-than-expected expenses.
Worst Case
Assumes weaker sales, delayed customer payments, unexpected costs, or other financial pressure.
For example, ask:
What happens if revenue is 15% lower than expected?
What happens if two major customers pay 30 days late?
What happens if our planned hire starts earlier than expected?
What happens if an unexpected $25,000 expense occurs?
Scenario planning turns a forecast into a decision-making tool.
Cash Flow Forecasting and Working Capital
Cash flow and working capital are closely connected.
Working capital is commonly calculated as:
Current Assets − Current Liabilities = Working Capital
However, positive working capital does not necessarily mean the business has comfortable cash reserves.
A large portion of current assets may be tied up in:
Unpaid invoices
Inventory
Other short-term assets
This is why businesses should monitor accounts receivable, accounts payable, inventory, and the cash conversion cycle together.
Timber Wolf’s working capital guidance highlights these relationships and explains how receivables, payables, and inventory can influence liquidity.
Cash Flow Forecasting and Financial KPIs
A forecast becomes more useful when it is connected to the right financial KPIs.
Depending on the business model, useful metrics can include:
Revenue growth
Gross margin
Net profit margin
Operating cash flow
Accounts receivable days
Accounts payable days
Working capital
Cash runway
Operating expenses
For example, if revenue is growing but accounts receivable days are also increasing, the business may be generating more sales without receiving the cash quickly enough.
Timber Wolf’s financial KPI guidance emphasizes that revenue alone does not provide a complete picture of financial health and that cash flow, margins, and working capital should be considered together.
Common Cash Flow Forecasting Mistakes
Treating Revenue as Cash
A sale is not necessarily a bank deposit.
Ignoring Payment Timing
Customer payment terms can materially change short-term liquidity.
Forgetting Irregular Expenses
Taxes, insurance, equipment, annual subscriptions, and other non-monthly costs can create unexpected cash pressure.
Using Outdated Bookkeeping
If your financial records are several weeks or months behind, your forecast may start with inaccurate information.
Forecasting Only the Best Case
A single optimistic projection can hide financial risk.
Never Reviewing Variances
If you do not compare forecasted numbers with actual results, you miss opportunities to improve your assumptions.
Ignoring Working Capital
Rapid growth can consume cash when more inventory, receivables, or operating resources are required.
How to Improve Cash Flow Forecast Accuracy
You do not need a complicated financial model to improve forecasting.
Start with these practices:
Use current financial data.
Keep bookkeeping and bank reconciliations up to date.
Base assumptions on actual history.
Use previous payment behavior, expense patterns, and seasonal trends where relevant.
Separate revenue from collections.
Forecast when customers are likely to pay rather than assuming every sale becomes immediate cash.
Include irregular expenses.
Review the upcoming calendar for taxes, insurance, equipment, debt, and other large payments.
Build scenarios.
Prepare for both downside and upside outcomes.
Review regularly.
Update assumptions when business conditions change.
The U.S. Small Business Administration also recommends comparing expected financial performance with actual results and using financial projections as part of ongoing business planning.
When Should a Business Get Professional Cash Flow Forecasting Help?
Professional support can become valuable when financial decisions become more complex.
Consider additional support if your business:
Frequently experiences cash shortages
Is growing rapidly
Has unpredictable customer collections
Is planning major hiring
Is considering expansion
Has significant inventory
Is preparing for financing
Is evaluating an acquisition
Needs more sophisticated financial reporting
Wants to compare multiple growth scenarios
A Fractional CFO can connect cash flow forecasting with budgeting, profitability analysis, financial KPIs, working capital, and strategic planning.
Timber Wolf’s current Fractional CFO offering includes these forward-looking functions rather than focusing only on historical bookkeeping.
Cash Flow Forecasting vs. Financial Forecasting
Cash flow forecasting is one part of broader financial forecasting.
Cash flow forecasting focuses specifically on expected cash availability.
Revenue forecasting estimates future sales.
Expense forecasting estimates future costs.
Profit forecasting estimates future profitability.
Scenario forecasting evaluates different possible outcomes.
Together, these models provide a more complete view of the company’s financial future.
Frequently Asked Questions
What is cash flow forecasting?
Cash flow forecasting is the process of estimating future cash inflows and outflows to determine how much cash a business may have available during a future period.
How do you forecast cash flow?
Start with the current cash balance, estimate customer collections and other inflows, list expected expenses and other outflows, account for timing, calculate projected closing cash, and compare forecasts with actual results.
What is the simplest cash flow forecast formula?
A basic formula is:
Opening Cash + Cash Inflows − Cash Outflows = Closing Cash
How far ahead should a small business forecast cash flow?
There is no universal period. Many businesses use monthly forecasts for planning while maintaining a shorter weekly view when cash is tight or unpredictable.
Is cash flow forecasting the same as budgeting?
No. A budget generally establishes planned income and expenses, while a cash flow forecast focuses on when cash is expected to enter and leave the business.
Can a profitable business still have cash flow problems?
Yes. A business can be profitable while experiencing a cash shortage if customers pay slowly, inventory consumes cash, or large expenses become due before expected collections arrive.
Final Thoughts
Cash flow forecasting is not about predicting the future perfectly. It is about seeing potential financial problems early enough to make better decisions.
A practical process looks like this:
Accurate Bookkeeping → Reliable Financial Data → Cash Flow Forecast → Scenario Planning → Variance Analysis → Better Decisions
Start with your actual cash position. Estimate realistic collections. Include every meaningful cash outflow. Pay attention to timing. Build multiple scenarios and compare your forecast with actual results.
Most importantly, keep the forecast connected to the broader financial picture.
Cash flow forecasting becomes significantly more valuable when combined with financial reporting, working capital management, financial KPIs, budgeting, profitability analysis, and strategic financial planning.
For businesses that need deeper financial visibility, Timber Wolf Analytics provides bookkeeping, financial reporting, cash flow forecasting, and Fractional CFO services designed to help owners move from simply understanding what happened to planning what should happen next.
2 Responses