How much of your bookkeeping should AI actually control?
Quick Answer:
What Should AI Automate in Bookkeeping?
- Receipt and invoice data extraction
- Transaction matching
- First-pass expense categorisation
- Duplicate detection
- Bank feed processing
- Recurring transaction identification
- Exception and anomaly detection
- Draft financial summaries
Let AI handle routine work, review anything unusual, and make sure people are responsible for financial judgment and final decisions.
What Is AI Bookkeeping?
- Reading receipts and invoices
- Extracting transaction details
- Suggesting account categories
- Matching payments with invoices
- Identifying duplicate transactions
- Flagging unusual expenses
- Preparing information for review
Automate Volume, Not Judgment
Does the correct answer come directly from the data, or does it require knowledge and judgment about the business?
| Receipt capture | Automate | Review exceptions |
| Invoice data extraction | Automate | Verify unusual information |
| Transaction matching | Automate | Resolve mismatches |
| Expense categorization | Suggest | Review unusual transactions |
| Bank reconciliation | Assist | Review unresolved differences |
| Financial reports | Generate | Interpret |
| Cash flow forecasting | Support analysis | Review assumptions |
| Payment approval | Assist workflow | Final approval |
| Tax decisions | Support research | Professional judgment |
| Financial strategy | Provide insights | Make decisions |
Splitting up these responsibilities makes your automated accounting system more reliable.
What AI Should Handle in Small Business Bookkeeping
1. Receipt and Invoice Data Capture
- Vendor name
- Date
- Amount
- Invoice number
- Payment terms
- Tax-related fields
Best practice
2. Transaction Matching
- Bank transactions
- Credit card transactions
- Customer payments
- Vendor invoices. This saves time you’d otherwise spend searching through financial records by hand. Financial records.
3. First-Pass Expense Categorisation
- Vendor history
- Previous transactions
- Transaction descriptions
- Historical coding patterns. This can save a lot of time when dealing with recurring expenses. expenses.
Best practice
- New vendors
- Unusual expenses
- Large transactions
- Rare categories
- Transactions that affect important financial metrics. Automation should speed up the review process, not eliminate it. te it.
4. Identifying Duplicates and Unusual Transactions.
One big advantage of AI is that it can quickly scan lots of financial data to find patterns. terns.
- Possible duplicate invoices
- Unexpected spending
- Unusual payment amounts
- Missing transactions
- But that doesn’t mean AI always knows if something is truly wrong.
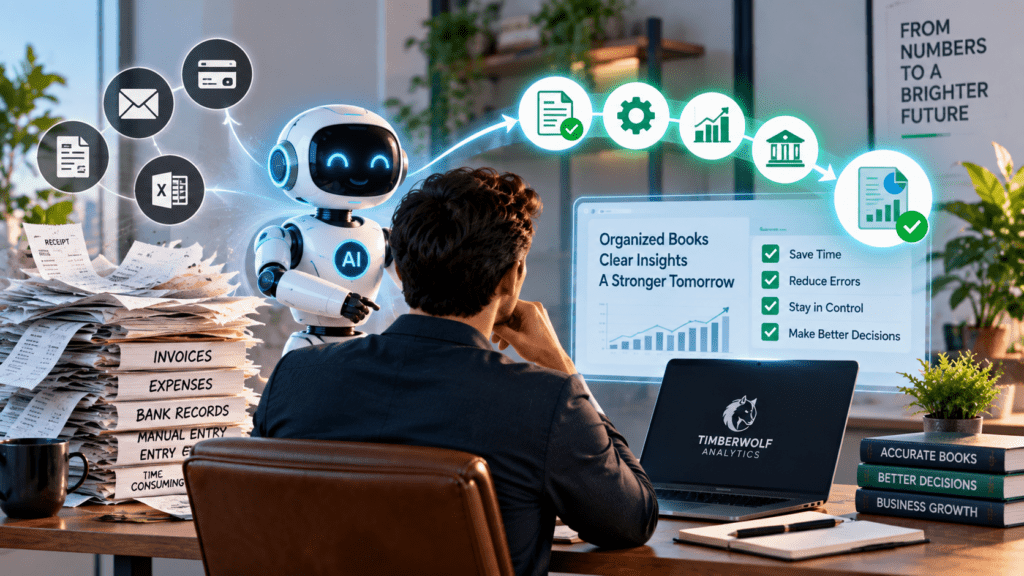
What You Should Never Fully Automate. Not every financial task should go straight from automation to action.
1. Payment Approval and Money Movement
- Approve payments
- Release transfers
- Change payment amounts
- Add new payees
2. Tax and Compliance Judgment
3. Strategic Financial Decisions
- Which employees are essential
- Customer relationships
- Growth opportunities
- Competitive risks
- Long-term business strategy
How AI Can Create Bookkeeping Mistakes. One of the biggest risks with automation isn’t just obvious mistakes made by AI.
- The transaction is posted automatically.
- The error affects financial reports.
- No one reviews the exception.
- The same pattern is repeated in future transactions.
Step 1: Define What AI Is Allowed to Do
- What information AI can access
- What output it can produce
- Whether it can create a draft
- Whether human approval is required
Step 2: Use Review Queues
Review when they involve:
- New vendors
- Large amounts
- Unusual categories
- Missing documentation
- Low-confidence suggestions
- Duplicate warnings
- Where the transaction came from
- Which document supported it
- What AI suggested
- What was changed
- Who approved the final result?
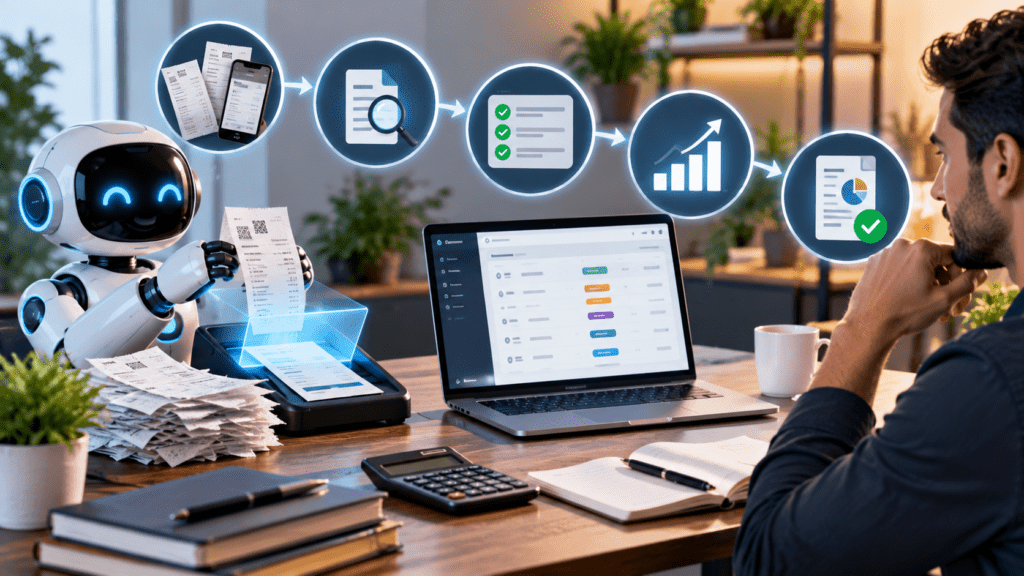
Automation doesn’t take away the need to reconcile your accounts.
Regular reconciliation remains one of the best ways to identify:
- Missing transactions
- Duplicate entries
- Incorrect entries. AI can help make reconciliation faster. Make reconciliation faster.
Make sure your financial records match your actual financial activity. ecisions
This is where AI bookkeeping can really make a difference keeping work faster.
Use less time collecting data and more time understanding what it means. Business owners can spend more attention on questions such as:
- Is cash flow improving?
- Which expenses are increasing?
- Are margins changing?
- Which customers are most profitable?
- How much cash is available for growth?
- What could happen under different financial scenarios?
This naturally links your bookkeeping, financial reports, and cash flow forecasts. The next step is understanding what those numbers may mean for future decisions.
This is also where TimberWolf Analytics’ Fractional CFO services can add value by helping businesses move from recording financial information toward forecasting, planning, and strategic decision-making.
Will AI Replace Accountants and Bookkeepers?
In short, AI is more likely to change how the work is done than to replace professional judgment fully. AI can automate many repetitive tasks that traditionally consume bookkeeping time.
But bookkeeping and accounting involve more than entering transactions. Professionals may still be needed to:
- Review unusual activity
- Apply business context
- Exercise professional judgment
- Manage controls
- Interpret financial reports
- Address tax and compliance issues
- Help business owners make decisions
Research in 2026 still shows that AI can’t fully replace human judgment in accounting, especially for accountability and complex decisions.
The likely direction is not simply:
AI vs. Bookkeeper
Final Thoughts: Don’t Put Your Books on Autopilot
AI can make small business bookkeeping faster and more efficient.
But being faster doesn’t mean you control your finances.
The most reliable approach to AI bookkeeping for small businesses is to establish clear boundaries:
Let AI handle:
- Data capture
- Repetitive processing
- Matching
- First-pass categorisation
- Pattern detection
- Exception identification
Keep humans responsible for:
- Final approvals
- High-risk transactions
- Payment decisions
- Tax and compliance judgment
- Financial interpretation
- Business strategy
The goal isn’t to automate everything. The goal is to automate the right things.
When AI handles routine work and people stay involved, small businesses can cut manual tasks without losing confidence in their financial information.
The best AI bookkeeping system, therefore, isn’t one that removes humans from the process.
It helps people spend less time on repetitive tasks and more time making smart financial decisions.