Selling more does not always mean having more cash available. A small business can generate strong revenue and still face financial pressure when customers take too long to pay their invoices.
That is why accounts receivable aging and days sales outstanding (DSO) are important financial measures for small businesses. An aging report shows which invoices are current or overdue, while DSO Accounts Receivable Aging estimates how quickly a business collects its credit sales.
Used together, these tools can help business owners identify collection problems, improve cash flow visibility, manage working capital, and make better financial decisions.
This guide explains what accounts receivable aging is, how aging works, how to Accounts Receivable DSO, how to interpret the results, and practical ways to improve collections.
What Is Accounts Receivable?
Accounts receivable Aging (AR) is money customers owe a business for products or services that have already been provided but have not yet been paid for.
For example, a consulting company completes a $5,000 project and sends its client an invoice with payment due in 30 days. Until the customer pays, the $5,000 is recorded as an account receivable.
Accounts receivable aging is therefore an important part of a company’s Accounts Receivable current assets and working capital. TimberWolf Analytics also explains that receivables can affect cash availability because revenue may be recorded before the related cash is collected.
The problem begins when outstanding invoices remain unpaid longer than expected. At that point, revenue Accounts Receivable aging may look healthy while available cash becomes tighter.
What Is Accounts Receivable Aging?
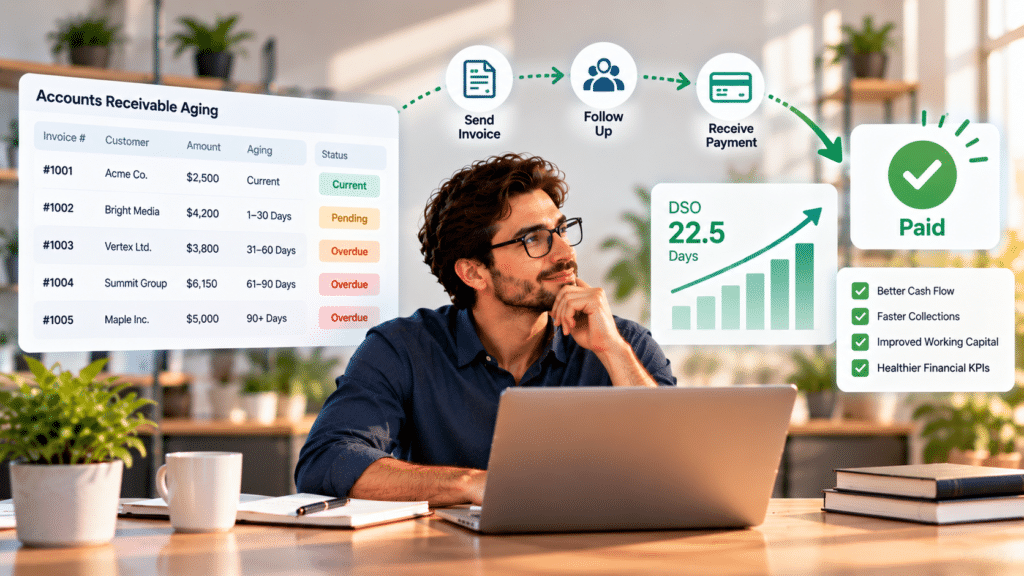
An accounts receivable aging report organizes unpaid invoices according to how long they have been outstanding.
Common aging categories include:
| Aging Category | What It Usually Means |
|---|---|
| Current | Not yet overdue |
| 1–30 days | Recently overdue |
| 31–60 days | Moderately overdue |
| 61–90 days | Significantly overdue |
| 90+ days | High-priority collection account |
Businesses may customize these categories depending on their payment terms, industry, and collection process. Aging reports generally include the customer, invoice date, due date, amount owed, and age of each receivable.
The purpose is not simply to create a report. It is to identify where cash is getting stuck and which invoices require action.
Why Accounts Receivable Aging Matters for Small Businesses
Large companies may have more liquidity to absorb delayed customer payments. Small businesses often have less room for that delay.
Consider a company with $100,000 in outstanding invoices. If most of the balance is current, the risk may Accounts Receivable Aging be manageable. But if $40,000 has been unpaid for more than 60 days, management may need to investigate immediately.
An aging report can help identify:
Customers who repeatedly pay late
Large overdue balances
Billing or invoice disputes
Concentration of receivables among a few customers
Collection problems
Potential bad debts
Changes in payment behavior
It can also support cash flow forecasting because expected customer payments are an important part of future cash inflows. TimberWolf’s cash-flow guidance emphasizes starting forecasts with reliable financial information and expected customer payments.
What Is Days Sales Outstanding (DSO)?
Days sales outstanding (DSO) measures the average number of days a business takes to collect payment after making a credit sale.
A commonly used formula is:
DSO = (Average Accounts Receivable Aging ÷ Total Credit Sales) × Number of Days in the Period
For example, suppose a business has average accounts receivable aging of $30,000 and $120,000 in credit sales over a 90-day period.
DSO = ($30,000 ÷ $120,000) × 90
DSO = 22.5 days
That means the business collected its credit sales in an average of approximately 22.5 days during that period. The interpretation depends on the company’s payment terms and industry.
A lower DSO generally indicates faster collections, but there is no universal DSO number that is automatically “good” for every business. A company offering net-30 terms will have a different benchmark from one with net-60 terms.
How to Calculate DSO Step by Step
To calculate DSO accurately:
1. Choose the measurement period
Use a consistent period such as 30, 90, or 365 days.
2. Calculate average accounts receivable aging
A simple approach is:
Average AR = (Beginning AR + Ending AR) ÷ 2
For businesses with significant fluctuations, more frequent averages can provide a better picture.
3. Determine credit sales
Use credit sales for the same period rather than mixing unrelated revenue figures.
4. Apply the DSO formula
Divide average accounts receivable aging by credit sales and multiply by the number of days in the period.
5. Compare the result
Compare the current DSO with:
Previous periods
Contractual payment terms
Internal targets
Business or industry expectations
The trend can be more useful than one isolated number.
Accounts Receivable Turnover Ratio vs. DSO
The accounts receivable aging turnover ratio and DSO measure related aspects of collection performance.
The receivables turnover ratio generally looks at how many times a business collects and replaces its average receivables during a period.
A simplified formula is:
Accounts Receivable Turnover = Net Credit Sales ÷ Average Accounts Receivable Aging
DSO looks at the same collection cycle from a days perspective.
In general:
Higher receivables turnover = faster collection
Lower DSO = faster collection
These metrics should be interpreted together with payment terms and business circumstances rather than viewed in isolation.
Accounts Receivable Aging vs. DSO
Although both metrics relate to collections, they answer different questions.
Accounts receivable aging asks:
“Which invoices are overdue, and how long have they been outstanding?”
DSO asks:
“How many days does it take us to collect credit sales on average?”
For example, a business can have a reasonable DSO while still having one major customer with a seriously overdue invoice.
That is why DSO should not replace an aging report.
A strong accounts receivable aging process uses both:
Aging Report → Identify Problem Invoices
DSO → Measure Overall Collection Speed
How to Use an Aging Report to Get Paid Faster
An aging report becomes valuable when it leads to specific action.
Prioritize the oldest and largest balances
Start with invoices that are both significantly overdue and financially material. A $25,000 invoice that is 75 days late deserves a different level of attention than a $200 invoice that is three days overdue.
Contact customers before invoices become severely overdue
Collections should not begin only after an invoice has become a major Accounts Receivable problem. Establishing a consistent follow-up schedule can make payment expectations clearer.
Investigate disputes quickly
Some overdue invoices are not collection problems at all. They may involve Accounts Receivable incorrect billing, missing documentation, purchase-order issues, or service disputes.
Resolving the underlying issue can be more effective than repeatedly asking for payment.
Make payment instructions easy to follow
Invoices should clearly show the amount due, due date, accepted payment methods, and relevant payment instructions.
Review repeat late payers
A customer who consistently pays late may require different credit terms, stronger communication, deposits, Accounts Receivable milestone billing, or management review.
Any changes should fit the company’s contracts, customer relationships, and business model.
How Accounts Receivable Affects Cash Flow and Working Capital
Accounts receivable directly affects the timing of cash entering a business.
Suppose a business completes $50,000 of work this month and Accounts Receivable invoices its customers. The revenue may be recorded, but the company may still be waiting for that $50,000 to become cash.
This creates an important distinction:
Revenue is not the same as cash collected.
When receivables grow faster than collections, more of the company’s resources can become tied up in unpaid invoices. TimberWolf’s working capital guidance specifically identifies accounts receivable Accounts Receivable as a component of working capital and recommends monitoring overdue invoices and customer payment patterns.
Better AR management can therefore support:
Cash flow management
Working capital management
Financial planning
Cash flow forecasting
Short-term liquidity
More predictable business operations
How Bookkeeping Supports Accounts Receivable Management
Effective receivable management depends on accurate financial records.
Small business bookkeeping helps keep customer balances, invoices, payments, credits, and adjustments organized. Reliable records make it easier to reconcile receivables and produce useful financial reports.
A practical process looks like this:
Accurate Bookkeeping → Reliable Financial Reporting → AR Visibility → Collection Action → Better Cash Flow
Without accurate bookkeeping, an aging report may contain Accounts Receivable incorrect balances or payments that have not been properly recorded.
TimberWolf’s existing accounts receivable guidance also connects AR visibility with bookkeeping, cash flow analysis, working capital, and financial decision-making.
Financial KPIs to Monitor With Accounts Receivable
DSO should be part of a broader group of financial KPIs, rather than the only number management reviews.
Depending on the business, useful measures may include:
Days Sales Outstanding
Accounts receivable turnover ratio
Total outstanding receivables
Percentage of overdue invoices
Aging by customer
Bad-debt write-offs
Cash collected versus billed
Revenue growth
Operating cash flow
Working capital
The goal is to connect collection performance with the company’s overall financial health. TimberWolf recommends Accounts Receivable selecting KPIs that support meaningful business decisions rather than tracking every available metric.
Accounts Receivable vs. Accounts Payable
A common question is: What is the difference between accounts receivable and accounts payable?
Accounts receivable is money customers owe your business.
Accounts payable is money your business owes suppliers and vendors.
Both affect working capital and cash flow, but they represent opposite sides of the business’s short-term financial obligations.
Managing receivables means improving the timing and reliability Accounts Receivable of incoming cash, while managing payables means controlling outgoing payments without missing important obligations.
Together, they provide a clearer view of short-term liquidity.
Common Accounts Receivable Mistakes
Small businesses often create collection problems by:
Sending invoices late
Using unclear payment terms
Failing to track overdue balances
Waiting too long to follow up
Not reconciling customer payments
Ignoring recurring disputes
Measuring revenue without monitoring collections
Relying only on the bank balance
Failing to update cash flow forecasts
A professional financial reporting process can make these issues easier to identify before they become significant cash-flow problems.
How Often Should You Review Accounts Receivable Aging?
For many small businesses, reviewing AR at least weekly can provide useful visibility, particularly Accounts Receivable when cash flow is tight or customers frequently pay on different schedules.
At minimum, management should review aging during the regular financial close and whenever a significant cash-flow decision is being made.
The appropriate frequency depends on invoice volume, payment terms, customer concentration, and financial risk.
The key is consistency.
Frequently Asked Questions
What is meant by accounts receivable?
Accounts receivable is money owed to a business by customers for goods or services that have already been provided but have not yet been paid for.
What is an accounts receivable aging report?
It is a report that groups unpaid customer invoices according to how Accounts Receivable long they have been outstanding, commonly using current, 1–30, 31–60, 61–90, and 90+ day categories.
What is the formula for calculating DSO?
A commonly used DSO formula is:
DSO = (Average Accounts Receivable ÷ Total Credit Sales) × Number of Days in the Period.
What does a high DSO mean?
A high DSO generally means customers are taking longer to pay. However, the result should be compared with payment terms, historical performance, and the company’s business model.
How can a small business reduce DSO?
Start by invoicing promptly, setting clear payment terms, monitoring aging, following up consistently, resolving disputes quickly, and making payment instructions easy to use.
What is the difference between AR turnover and DSO?
AR turnover measures how frequently receivables are collected during a period, while DSO expresses collection performance as an average number of days.
Final Thoughts
Accounts receivable management is not simply about chasing overdue invoices. It is about creating a reliable system for turning sales into collected cash.
An accounts receivable aging report shows where unpaid invoices are concentrated. DSO shows how quickly the business is collecting on average. The accounts receivable turnover ratio adds another perspective on collection efficiency.
When these metrics are supported by accurate small business bookkeeping, financial reporting, cash flow management, working capital management, and financial planning, owners can gain much stronger visibility into the company’s financial position.
The objective is simple: know what customers owe, understand when cash is likely to arrive, act on collection risks early, and use reliable financial information to make better business decisions.